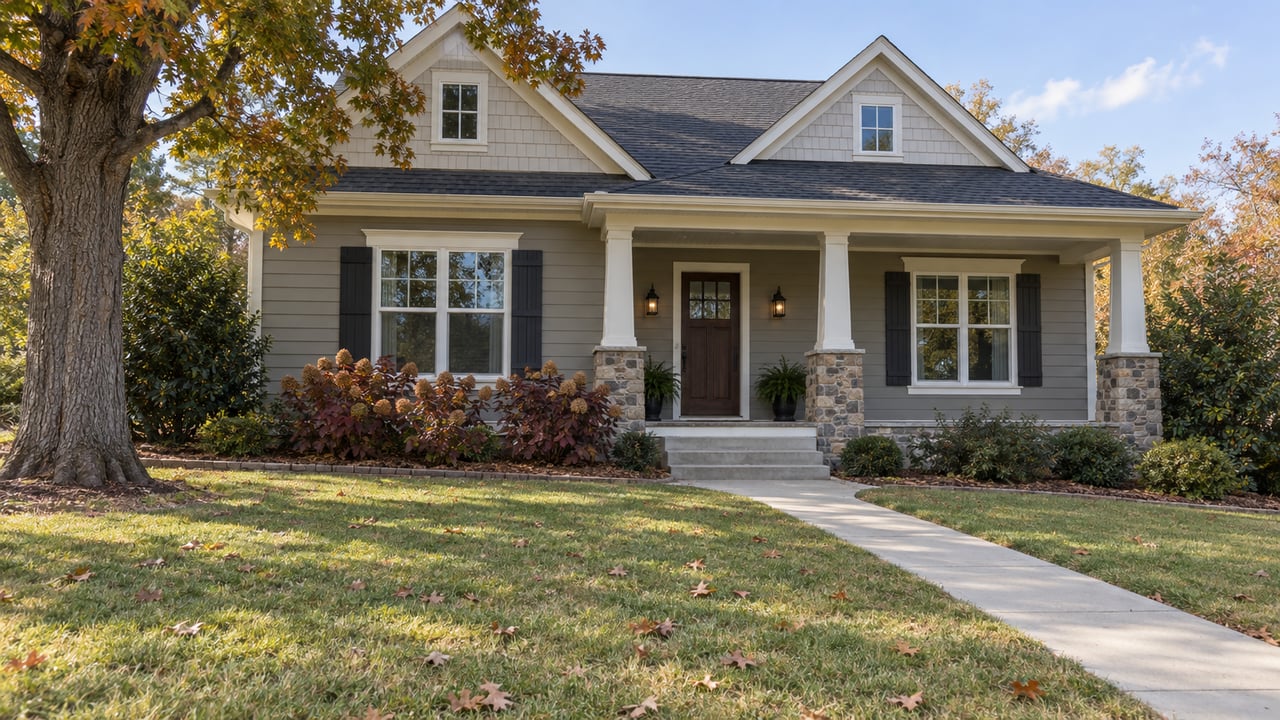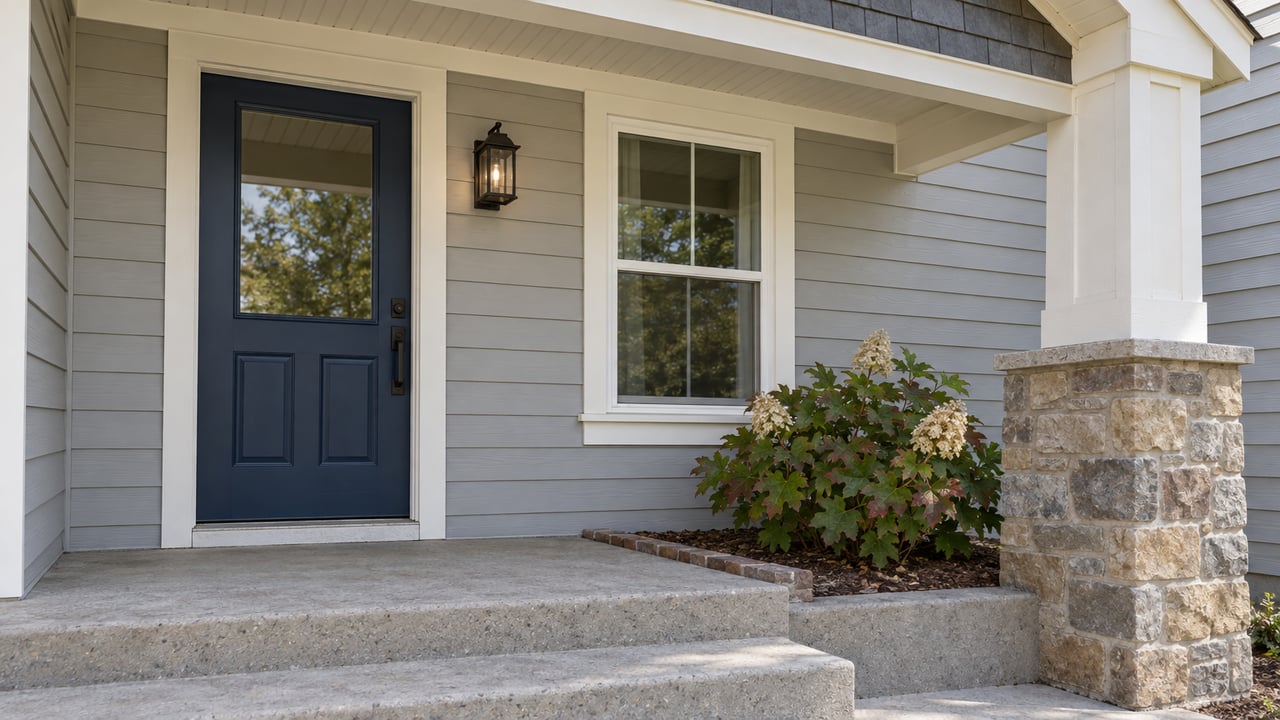
The listing for 6238 Canterbury Farms Parkway in Tillery Park shows $434,900 for a four-bedroom, 2,724-square-foot Maple 2 plan by First Choice Home Builders. The most important line on that page sits underneath the price. It's a $25,000 builder incentive the buyer can put toward a rate buydown, a price reduction, appliances or blinds. "Buyer Chooses!" That choice is where most of the money in a Grovetown new-construction purchase gets decided this fall. It also explains why the asking prices on new homes around Grovetown have stopped describing what those homes actually cost.
What Grovetown Builders Are Offering This Month
Nearly every active builder in the Grovetown area is selling with an incentive attached as of late September 2026. Few are selling with a lower base price. Here's what their own pages show:
- Ivey Homes at Tillery Park and Crawford Creek: A $4,000 base incentive, plus $2,000 more for September contracts, with select move-in-ready homes reaching up to $14,000. Ivey's homepage lists the September event as running through 9/30, which is today.
- Ivey Homes, Declaration Homes at Tillery Park West: $8,000 in incentives, plus $2,000 for September contracts. Georgia presale buyers get $8,000 and lock 2026 pricing for a 2027 move-in.
- Bill Beazley Homes at Misty Meadows: On qualifying homes, rates as low as 4.99%, $10,000 toward closing, $7,000 for upgrades, closing costs or a buydown, or $5,000 in Movement Mortgage lender credits. Active homes there range from $374,900 to $419,900.
- D.R. Horton at Estates at Deer Hollow and Captain's Corner: Both communities are marked "Closing Out," with a "Special Interest Rate" on select homes. The one visible price change in the set is a $1,000 reduction on 5160 Captain Drive.
- First Choice Home Builders in Tillery Park: The $25,000 buyer's-choice incentive at Canterbury Farms Parkway.
Ivey alone showed 43 quick move-in homes on its Grovetown page, across four selling communities priced from $210,000 to $512,000. That's a lot of finished product, and the response has been to add money on top of the price rather than take money off it.
Why the Number on the Listing Stays Put
Housing economist Brad Hunter laid out the logic in a September 4, 2026 Forbes analysis. Large builders own captive mortgage companies, and they use them to sell a payment instead of a price:
"A forward commitment or a permanent buydown lowers the payment without marking down the base price. That protects appraisals, protects the comparable sales for the rest of the community, and protects the equity of the buyer who closed last quarter."
In Grovetown, the phrase "the rest of the community" covers a lot of future lots. In April 2026, Ivey Development proposed Light Hill Creek, a 177-lot subdivision connected to Tillery Park, with construction phases projected from 2026 through 2029. Grovetown City Council's September 14, 2026 agenda included a second reading on annexing and rezoning 4.053 acres at 770 Chamblin Road for residential use. Back in May, WRDW reported that a separate proposal for a 56-home subdivision on Chamblin Road had a planning-commission recommendation for approval and was headed to Grovetown City Council. Nearby, the Augusta Chronicle reported a July request to add 38 homes to Bartram Trail.
Every closed sale in Tillery Park today becomes a comparable sale for the homes that follow it. A $25,000 price cut would record a lower sale price. A $25,000 buydown leaves the recorded price at $434,900. For a builder planning years of future phases next door, that difference matters more than any single sale.
The Choice at Canterbury Farms Parkway
That puts the buyer of a home like 6238 Canterbury Farms Parkway in an unusual position. The same $25,000 can do two very different jobs.
Spent on a price reduction, it lowers the amount you borrow and the sale price recorded against the home. Spent on a rate buydown, it lowers the monthly payment while the recorded price stays put. Hunter's Forbes example shows how much a buydown can do. On a $354,420 loan, a 4.9% rate produces a payment of $1,881, compared with $2,329 at 6.88%. That's roughly $448 a month. In August, borrowers using builder-affiliated lenders locked at about 5.23% on average, against 6.60% through unaffiliated lenders.
The right answer depends on the household. It turns on how long you expect to keep the loan, how close your purchase price lands to the appraisal, and whether the monthly figure or the total debt is the harder limit. Those are questions for your lender and your own planning. The thing to understand going in is that the builder doesn't care much which one you pick, as long as the recorded price holds. That's why "buyer chooses" exists at all.
A few incentives come with a lender attached, such as the $5,000 in Movement Mortgage credits at Misty Meadows. Get that offer in writing and compare it against an outside loan quote on the same day.
What a Grovetown Resale Seller Is Up Against
This is where the new-build pricing reaches the existing homes around it. Hunter puts it plainly: "A builder-financed buyer at 4.9% simply is not competing with the resale market at 6.9%. They are shopping in a different market."
Picture a resale home a few minutes from Tillery Park, listed near the same price as a new build. Its buyer typically finances at the market rate. The new-build buyer may be financing well below it. The list prices look comparable. The monthly payments are not. That puts a resale seller in Grovetown in a price contest whose real terms appear on loan estimates rather than in listing photos. Sellers who price against the new-build list price alone are measuring against a number the builders themselves are working around.
The national data fills in the rest. In August 2026, according to the NAHB/Wells Fargo Housing Market Index, 35% of builders cut prices, by an average of 6%, while 63% used some form of sales incentive. In its fiscal third quarter ended August 31, 2026, Lennar reported an average sales price of $372,000 with incentives of about 12.0%. A resale owner who can't offer a 4.9% loan has to compete through condition, presentation and seller concessions structured to land in the buyer's monthly figure.
Why This Window Probably Won't Stay Open
Hunter's September analysis argues that the peak in builder incentives "has almost certainly passed." Builders began pulling concessions back in the second quarter of 2026. Then mortgage rates climbed toward 6.9%, making each point of buydown more expensive just as builders had promised investors they'd spend less on it. On July 21, 2026, D.R. Horton said it expected sales incentives to remain elevated through its fiscal fourth quarter, with the level depending on demand, rates and market conditions.
Locally, several of the most generous offers are attached to communities near the end of their run:
- Estates at Deer Hollow and Captain's Corner are both marked "Closing Out."
- Stanley Martin calls Ferguson Farms a "Final Opportunity," with three move-in-ready homes listed from $324,900 to $388,745.
- Ivey's Grovetown communities page lists Crawford Creek at "2 Homes Left! Final Opportunity!" with prices from $444,900 to $484,900.
- Hughston Homes' Hamilton Grove showed three homes under construction, priced $439,900 to $479,900, and none available now.
More supply is still coming. Dr. Simon Medcalfe of AU's Hull College of Business reported in Augusta Business Daily that Augusta-area residential permits in June 2026 hit their highest level since March 2025. More than 300 permits have been pulled every month since February 2026, a level reached in only four months during all of 2025. New phases mean new homes to sell. They also mean the base prices on today's closings will carry forward as the reference point for those phases.
Questions to Bring to a Builder's Sales Office
- Can the incentive go to price, rate or closing costs, and does the amount change depending on which one I pick?
- Does the rate offer require the builder's preferred lender, and what are the full loan terms compared with an outside quote?
- Is the buydown permanent or temporary, and what does the payment look like once any temporary period ends?
- Is the offer tied to a contract date, a closing date or a specific home? Ivey's September bonuses, for example, were tied to September contracts.
- What have comparable homes in this phase recorded as sale prices, before incentives?
FAQ
Are Grovetown builders cutting prices or adding incentives? Mostly adding incentives. Across the builder pages reviewed for September 2026, the one visible base-price cut was $1,000 on a single D.R. Horton home. Credits and rate offers ranged from several thousand dollars up to $25,000.
Will these incentives still be there in October? Some won't. Ivey's September bonuses were set to run through September 30, and builder promotions change often. Confirm current terms directly with each builder before you plan around a number.
How should a resale seller near Tillery Park price against new construction? Start from the monthly payment a buyer would face on your home compared with a builder-financed new build. List price alone won't capture that gap. Presentation and concessions are the tools a resale seller has to close it.
If you're weighing a Grovetown new build against a resale, or pricing your own home against the incentives down the road, The Moss Group can lay out what each offer means for your payment and your recorded price before you sign. Request a complimentary home valuation or schedule a consultation with Lisa.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.